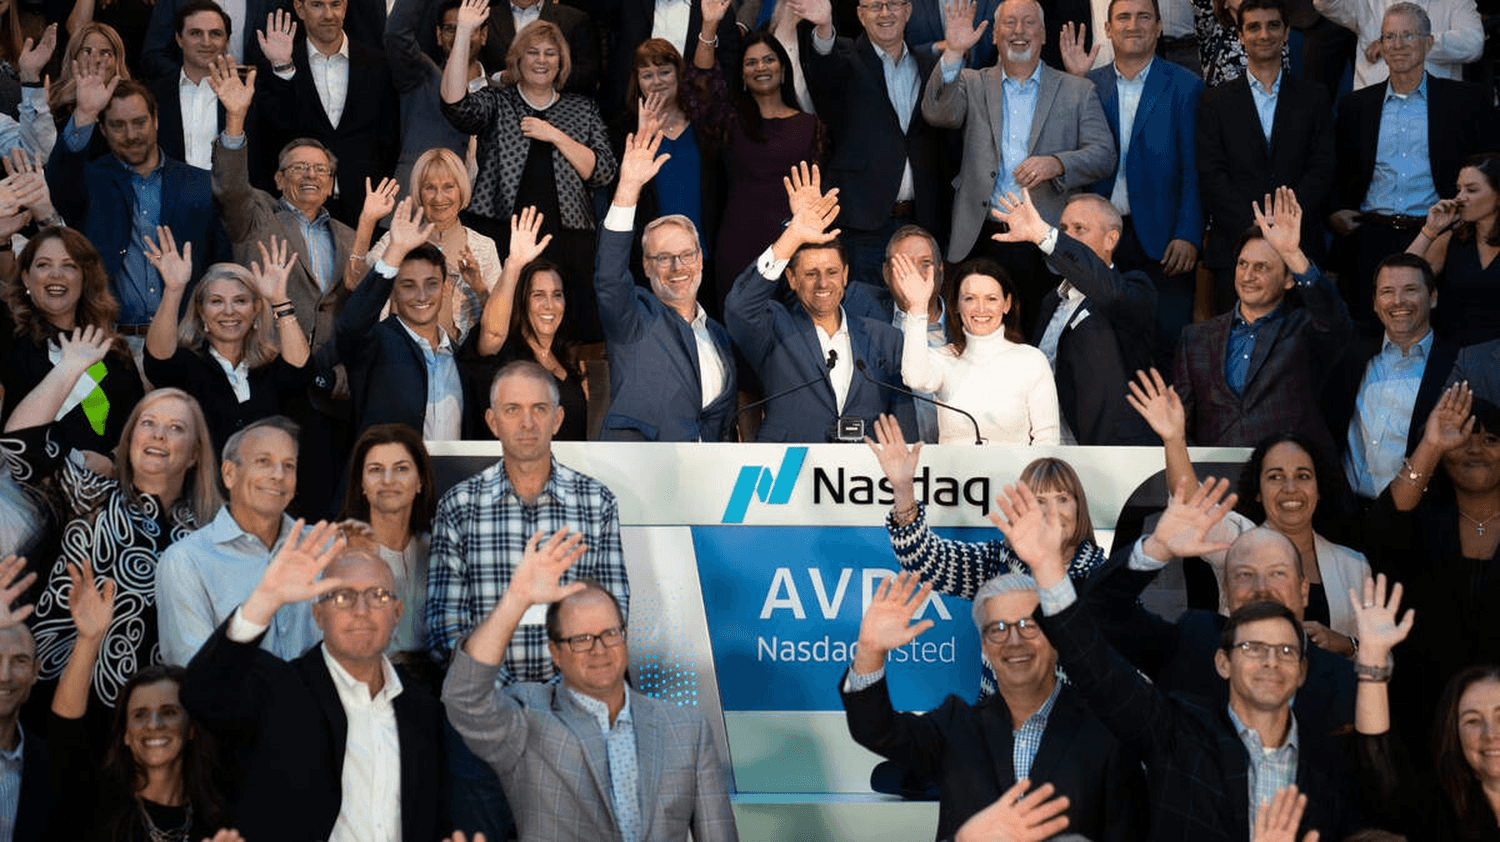
John Batdorf is meeting with data & AI founders at the Snowflake Summit. Request a meeting →

DATA & ANALYTICS

Everyone says they have proprietary data. Buyers have learned to check.

The premium in this market goes to companies whose data is genuinely hard to replicate and demonstrably useful inside a buyer's existing product. Not volume. Not a dashboard. A defensible position that an acquirer can plug in and monetize on day one. Proving that takes work, and it happens before diligence, not during it.

0+

Transactions completed firmwide

$0B+

Aggregate transaction value

0+

Cross-border deals transacted

YOUR BANKER

Meet the senior banker who will run your process.

John co-founded Nfluence and leads our Data & Analytics practice. With over 30 years of technology investment banking experience across SG Cowen, Viant Capital, and Headwaters MB, John brings deep strategic buyer access to every mandate.

John Batdorf executive discussion

Over three decades of technology investment banking experience. Key transactions include Adjust to AppLovin ($968M), Information Builders with Goldman Sachs and Bregal Sagemount, Near's acquisition of Teemo, TheMarkets.com to S&P Global, and Information Mosaic to Markit.

John Batdorf

John Batdorf

Managing Director, COO & Co-Founder

WHAT WE DO

Sell the company, or fund the next stage. Same preparation either way.

We advise founders of modern data stack, analytics, and AI infrastructure companies on maximizing transaction outcomes through strategic M&A and institutional growth rounds.

M&A advisory

Positioning data assets and software platforms to capture premium multiples from global strategics.

  • Sell-side M&A run across cloud hyperscalers, legacy software conglomerates, and tech PE
  • Strategic buy-side advisory for data platforms executing programmatic capability acquisitions
  • Cross-border M&A transactions across North America, Europe, and APAC
  • Carve-outs of enterprise data assets and specialized analytics divisions
  • Board advisory on unsolicited strategic approaches and consolidation offers
Capital formation

Securing growth capital engineered to accelerate customer acquisition and R&D pipelines.

  • Growth equity rounds from premier enterprise software and deep-tech sponsors
  • Structured debt, ARR credit facilities, and non-dilutive capital solutions
  • Majority and minority recapitalizations providing founder liquidity
  • Strategic corporate investments from major cloud and database providers
  • Cohort expansion audits, pipeline benchmarking, and transaction readiness

YOUR OPTIONS

One buyer is a negotiation. Several buyers is a market.
Every banker says they run a competitive process. Here is what actually changes depending on which route you take.

Run a full process

RECOMMENDED
Buyers at the table
Enough that no single party sets the terms

What you learn about the market

What the market will actually pay, priced by competition

Time required

Four to seven months

Disruption to the business

Highest, and planned for

Your negotiating position

Real alternatives, including walking away

Confidentiality

Managed deliberately, under NDA and staged disclosure

Timeframes are typical ranges for middle-market technology transactions and vary by company, sector, and market conditions.

M&ATravel & Hospitality Tech2026
Prismm

Acquired by Cvent (Blackstone)

Exclusive financial advisor to the seller

M&AEducation Technology2026
Wayfinder

Has been acquired by LEMNIS

Financial advisor on its sale to LEMNIS

Capital RaiseCrypto & FinTech2026
CoinFlip

Strategic recapitalization

Lead placement agent

M&AHospitality Software2025
vOffice

Acquired by Visit Group, a portfolio company of PSG

Financial advisor to the seller

M&AData & Analytics2025
NGL Labs

Has been acquired by Mode Mobile

Exclusive financial advisor to the seller

M&AHospitality Software2025
Easy Booking

Has been acquired by Zucchetti

Exclusive financial advisor to the seller

Capital RaiseHospitality & Events Tech2025
Prismm

Growth debt financing from Trinity Capital and Level Equity Financing

Lead placement agent

M&AFintech & Digital Assets2024
3iQ

Has been acquired by Monex Financial Group / Coincheck

Exclusive financial advisor to the seller

M&AHealthcare IT & Patient Access2024
SpinSci

Acquired by Aldrich Capital Partners
Exclusive financial advisor to the company

Capital RaiseHealthcare IT & RCM2024
PracticeSuite

Advised PracticeSuite on acquisition of MicroMD

Exclusive financial advisor to the buyer

Capital RaiseCreator Economy & MarTech2024
MagicLinks
Received financing from Heritage Bank of Commerce

Capital raise lead

M&APractice Management & EHR2024
MicroMD

Carve-out from Henry Schein acquired by PracticeSuite

Exclusive financial advisor to the buyer

M&AAccessibility Tech & GRC2024
UserWay

Acquired by Level Access, a portfolio company of KKR & JMI Equity

Financial advisor to the seller

M&ADental SaaS & HealthTech2024
Kleer

Has been acquired by Charlesbank Capital Partners

Exclusive financial advisor to the seller

M&APropTech & WealthTech2024
Cadre

Has been acquired by Yieldstreet

Exclusive financial advisor to the seller

Capital RaiseFintech & Accounting2023
Clearwater Analytics

Follow-on public offering

Financial advisor on follow-on equity offering

M&AInsurTech & Pension Software2023
WinTech

Has been acquired by Constellation Software

Exclusive financial advisor to the seller

M&ADigital Media & Music2023
LyricFind

Advised on strategic acquisition of Rotor Video

Exclusive financial advisor to the buyer

* Select transactions shown. Includes current Nfluence bankers' experience at prior firms. Full track record available upon request.

Deal TypeCategoryYear

Transaction Statement

THE MARKET READ

AI has changed what acquirers pay for.

$92.4B

Total enterprise spend on data infrastructure, analytics, and AI platforms in 2026.

78%

Of enterprise technology leaders prioritizing automated data governance and data quality.

6.5x

Median ARR multiple for high-growth data infrastructure platforms with consumption-based expansion.

The Argument

AI has changed what acquirers pay for. Tooling is commoditizing while proprietary data and the pipelines that produce it are appreciating. That is a genuine repricing, and companies that were valued as software two years ago may now be valued as data assets, or the reverse. Knowing which side of that line you are on determines who you should be talking to.

Reason 01

For data software companies scaling past $10M ARR, valuation multiples diverge sharply based on net expansion rates (NDR > 120%), gross margins, and customer lock-in within enterprise data engineering teams. We run disciplined competitive processes that engage both incumbent infrastructure titans and private equity sponsors assembling comprehensive modern data platforms.

Gartner Data & Analytics Market Guide, Modern Data Stack Benchmark Reports, and Nfluence proprietary M&A data.

Las Vegas conference skyline

WHERE WE'LL BE

Meet us at the Snowflake Summit.

If you are going to San Francisco, twenty minutes on the floor is worth more than a call in July. John keeps a handful of slots open for founders thinking about the next eighteen months.

JUN02-052026
VENUE

Moscone Center. San Francisco, California

ATTENDING

John Batdorf, Managing Director, COO & Co-Founder

What the meeting is

Not a pitch, and not a booth conversation. Bring the question you would actually want answered before you run a process. What companies like yours traded for this year. Which acquirers are active in your category right now and which have gone quiet. Whether your timing is right or whether you are eighteen months early.

You will get a straight answer, and if we are not the right firm John will say so and point you somewhere better.

Book early

Snowflake Summit brings together global data infrastructure acquirers and corporate development teams. Meeting slots fill quickly.

Request a meeting at Snowflake Summit

Not going to Snowflake Summit? John is in San Francisco and New York regularly. Book a call instead.

FAQ

Questions data & analytics founders
ask first.

How do I know what my data company is worth?

Talk to us. We'll give you two numbers: the conservative one and the outlier. In data, the first question is whether you're valued as software or as a data asset, and AI has moved that line. Value then moves on net expansion, gross margin, and how hard your data is to replicate. The outlier usually comes from a buyer that can plug your data into an existing product on day one. Gary was a CTO before he was a banker, so he reads your stack the way that buyer's team will.

A hyperscaler or platform partner wants to buy us. Should we just negotiate?

Not yet. If you're built on or integrated with their platform, they know your usage better than anyone, and that shows up in their offer. Review your marketplace and partner agreements first. Then let us bring in competing strategics and the sponsors assembling data platforms.

How do we protect proprietary data and models during diligence?

Staged access, controlled by a senior banker. Buyers see samples, aggregated metrics, and architecture reviews first. Source data, models, and customer identities come later, under tighter terms, often through a clean team.

We're not ready to sell. Is it too early to talk?

No. Proving your data is defensible takes time. Buyers have learned to check claims about proprietary data. Documenting data rights, collection methods, refresh rates, and customer usage takes months. Start early and that proof is ready before diligence, not during it.

We want liquidity without selling. What are the options?

More than you'd think. Minority recaps, growth equity, and ARR-based credit can get early holders liquid while you keep control. We don't earn recurring fees from sponsors, so we have no reason to steer you toward one. We pick the structure that fits.

Are we a software company or a data company?

Buyers decide by what's hard to replicate. Tooling is commoditizing. Proprietary data and the pipelines that produce it are appreciating. Buyers look at data rights, collection methods, refresh frequency, and how embedded your data is in customer workflows. We work out which side of that line you're on, then pick buyers to match.

Do we actually own our data?

Buyers will ask, so answer it first. Licensed, scraped, and customer-contributed data each carry different rights. If your licenses restrict transfer or AI training use, value drops. We review data rights with your counsel before buyers do.

We have usage-based pricing. How do we prove stickiness?

With cohorts. Show net expansion by cohort, consumption retention, and how usage grows as customers scale. Buyers pay more for predictable consumption growth than for seat counts. Volatile usage needs explaining before diligence finds it.

How do privacy laws affect our valuation?

Directly, especially if you touch personal data. Identity, location, and enrichment businesses get the closest scrutiny. Buyers want consent records, data lineage, and a clean regulatory history. Strong privacy posture is now a selling point. Gaps get priced as risk.

Is AI helping or hurting our valuation?

It depends on where you sit. If you supply the clean data, pipelines, or governance that AI depends on, demand has gone up. If a foundation model can now do what your product does, buyers will discount. We'll show you how buyers are pricing your category right now.